Managing money becomes noticeably harder when it belongs to more than one person. A household may have separate bank accounts, shared bills, personal spending, investments, and different ideas about what “under control” actually means. I tested Monarch as a finance app with that kind of everyday situation in mind, rather than treating it as a simple expense notebook. My first impression is that it works best as a shared financial overview: a place to understand the household picture, spot changes, and make better decisions before the month gets away from you.
Monarch is developed by Monarch Money and sits in the finance category. It is free to install, rated for Everyone, and has built a strong audience with an average score of 4.8 from roughly 24 thousand ratings. That popularity matters less to me than the way the app handles the awkward middle ground between private finances and shared responsibilities. It is not merely a calculator for adding receipts; it is designed around spending, net worth, investments, and financial goals.
How the app feels in a shared household
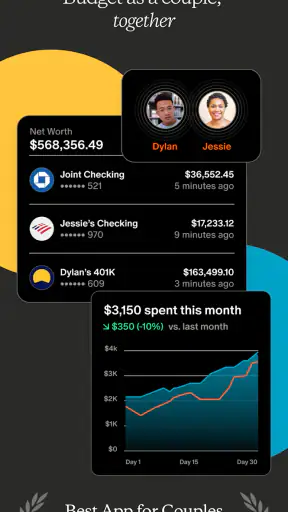
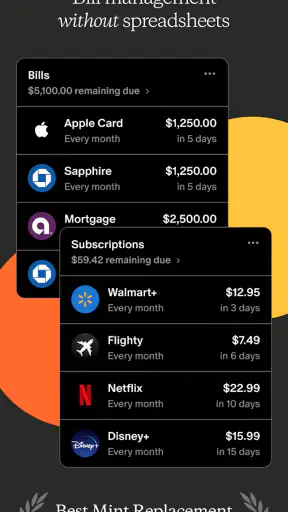
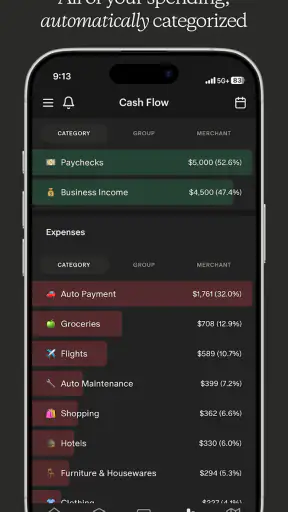
The most useful household scenario is a couple or family trying to answer practical questions together: How much did we spend on food this month? Are subscriptions quietly growing? Is the emergency fund moving in the right direction? What changed since the previous month? Instead of opening several banking apps and mentally combining balances, Monarch gives those questions a common place to start.
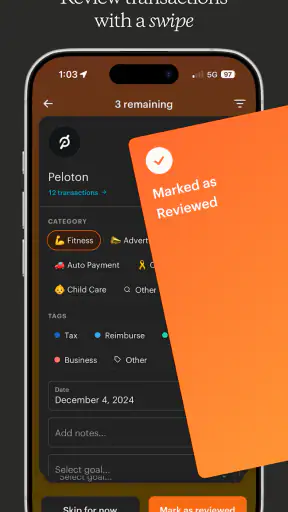
I especially like the idea of using it during a short weekly money check-in. One person can look through recent transactions while the other checks upcoming obligations and broader account balances. That is more productive than discussing money only after a bill is missed or a card statement becomes uncomfortable. The app’s value comes from turning scattered financial activity into something both people can discuss with the same context.
That does not mean every account should automatically become a shared account inside the app. A household can have joint finances and still need personal boundaries. I would decide in advance which accounts belong in the shared view, which spending categories are useful to discuss together, and which details should remain private. The important point is that Monarch can support coordination only when the people using it agree on what their shared financial picture should include.
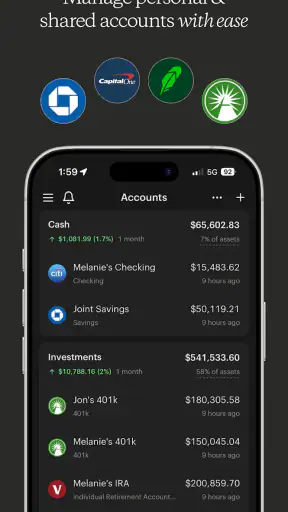
For a household with one income, several income sources, or irregular spending, the broader view is more helpful than a basic budgeting spreadsheet. A spreadsheet can be wonderfully flexible, but it depends on someone remembering to update it and maintain its formulas. A bank app is usually better for the individual account it represents. Monarch occupies the space between those options by helping me look across the whole financial setup instead of one institution at a time.
Setting boundaries before connecting accounts
My strongest setup advice is to begin with the purpose of the shared view, not with every account you can find. If the goal is planning household bills, start with the accounts that pay those bills and the balances that affect them. Adding every personal account immediately can make the overview feel complete, but it may also create unnecessary tension or clutter.
This matters because financial visibility is not the same thing as financial cooperation. Two adults may want to coordinate rent, utilities, groceries, and savings while keeping certain personal purchases outside the conversation. Monarch should be treated as a tool whose usefulness depends on the boundaries you establish around it. I would discuss those boundaries before inviting another person to rely on the same picture.
The app is free to install, but in-app purchases range from about fifteen dollars to nearly two hundred dollars per item. That makes it sensible to explore the experience carefully before treating it as the permanent center of a household’s financial routine. The cost question is not just about the app itself; it is about whether the time saved and the clearer conversations are worth adding another paid service to the household budget.
During setup, I would also create a simple naming system for household goals and categories. A label such as “home repairs” is more useful than a vague savings label when two people are reviewing progress together. Likewise, categories should reflect decisions the household actually makes. If a category is too broad to guide action, seeing its total will not necessarily help anyone change behavior.
One less obvious trade-off is that a unified dashboard can make financial life look cleaner than it really is. A single total may hide timing issues, pending expenses, annual bills, or money that is technically available but already committed. I would use the overview to ask better questions, not as permission to spend whatever balance appears on screen.
Coordinating spending without turning money into surveillance
Monarch is most convincing when it supports conversations rather than replacing them. A household can use its spending view to notice that dining, transport, or recurring charges have changed, then decide together whether that change was intentional. The app provides a starting point; it cannot know whether an unusual purchase was a problem, a celebration, or a necessary one-off expense.
I found that distinction important for shared-device use. If a tablet or phone is passed around the home, the app should not be treated casually. A financial dashboard can reveal more than a balance: it may expose habits, priorities, and personal choices. I would keep the device protected and agree on who is allowed to review information, especially when children or guests might use the same hardware.
For couples, a useful workflow is to separate review from judgment. First, look at what happened. Next, identify transactions that need clarification. Only then decide whether the budget, category, or goal needs changing. This avoids the common mistake of turning a transaction list into an argument. Monarch’s value is higher when both people see it as a neutral record rather than a tool for checking up on each other.
The same approach helps with irregular income. Instead of assuming that a strong month will repeat, I would use the app to compare current spending with financial goals and known obligations. A household can then choose a conservative amount for discretionary spending and leave room for quieter months. The net worth and investment views are useful in this context because they shift attention from the next purchase to the direction of the household’s finances.
There is also a practical coordination benefit for households where one person normally manages all the money. A shared overview can make the system easier to explain. The second person does not need to learn every banking login or spreadsheet formula just to understand the general position. Still, I would not confuse visibility with backup. Both adults should know where essential bills are paid and how to access important accounts independently of the app.
Goals, net worth, and the danger of false precision
The combination of goals, net worth, investments, and spending gives Monarch a wider role than a receipt tracker. I prefer this approach for long-term planning because everyday spending is only one part of financial health. A household can reduce restaurant purchases and still make little progress if debt, savings, or major upcoming costs are ignored.
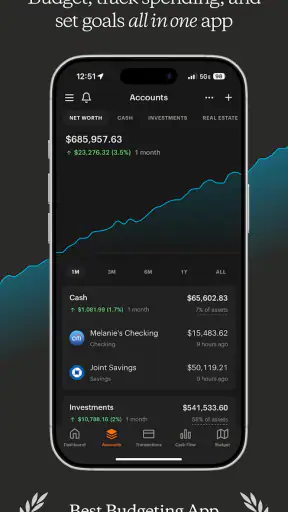
Net worth tracking can be motivating when used as a trend rather than a score. I would check it periodically, especially after meaningful financial changes, instead of reacting to every movement. Investment values naturally fluctuate, and a short-term change does not automatically mean the household made a good or bad decision. The app can show the direction of the numbers, but judgment still requires context.
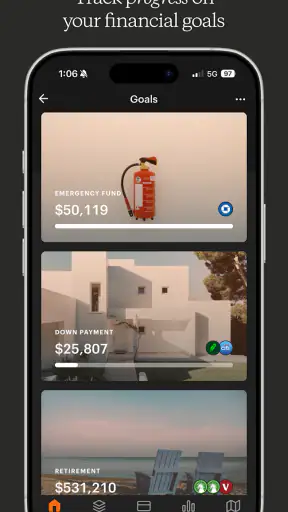
Goals are most effective when they are connected to a decision. “Save more” is too vague to alter behavior. A goal for replacing an appliance, building a cash reserve, or preparing for a planned trip gives the household a reason to review spending. When two people share the same target, progress becomes easier to discuss because the conversation is about a chosen priority rather than an abstract demand to spend less.
One advanced habit I recommend is reviewing goals alongside categories, not separately. If a household says it is prioritizing a goal but repeatedly redirects money toward less important categories, the mismatch becomes visible. That does not mean the app should dictate the answer. It simply gives the household a chance to decide whether the goal is unrealistic, the category is underestimated, or the priority has changed.
The limitation is that no dashboard can remove ambiguity from financial data. A transaction may need correction, a transfer may look like spending, or a balance may not represent money that can safely be used. I would verify important decisions against the relevant account before moving money. Monarch is a planning and understanding tool, not a substitute for checking the source when accuracy has immediate consequences.
Age, trust, and who should use it
The Everyone content rating makes the app broadly suitable from an age-classification perspective, but that does not mean every child should have unrestricted access to household finances. Money information is sensitive even when the app is easy to understand. For a family device, I would keep adult financial reviews separate from casual child use and avoid presenting account details as something anyone can browse.
Older teenagers may benefit from seeing how categories, goals, and long-term balances connect, but I would use selected conversations rather than handing over the entire household picture. The educational value comes from explaining decisions: why an emergency reserve matters, why investments can change value, and why a high balance is not the same as unlimited spending money. The app can support those lessons, but the adult still needs to provide the explanation.
Trust is equally important between adults. Monarch is not the right answer for a relationship where one person is being pressured to disclose private spending or where financial access is unsafe. A shared finance app should make agreed cooperation easier, not create a new way to monitor someone. If privacy boundaries are unclear, I would resolve that issue before connecting accounts or sharing a device.
I would also skip this app if I wanted only a private, manual spending log with no broader financial picture. A simple notes app or spreadsheet may be enough for someone who dislikes account aggregation and prefers entering every expense by hand. Likewise, households that already have a reliable system inside their bank may not gain enough from adding another dashboard unless they specifically want cross-account net worth, investment, and goal tracking.
Where it stands against familiar alternatives
Compared with a traditional budgeting spreadsheet, Monarch should be easier for a household that wants an ongoing overview without maintaining formulas and tabs. The spreadsheet wins when I need unusual calculations, complete control over layout, or a fully manual process. Monarch wins when the priority is seeing spending, accounts, investments, and goals in one finance-focused environment.
Compared with individual bank applications, it is more useful for a household with accounts spread across institutions. A bank app is usually excellent for transactions and balances at that bank, but it does not naturally provide the same cross-household perspective. The trade-off is that another layer of organization can introduce review work and subscription cost, so the broader view needs to be something the household will actually use.
Compared with a basic expense tracker, Monarch feels more appropriate for people who care about net worth and longer-term progress, not just recording purchases. A lightweight tracker may be quicker for someone who wants a daily spending diary. I would choose Monarch when the real question is “How are we doing overall?” rather than “What did I buy today?”
The app has been available since January 21, 2021, and its current version is 2.0.112. It supports devices running Android 7.0 or later, which makes it accessible on many older Android phones and tablets. That compatibility is convenient for a household using a shared or spare device, although I would still make sure the device itself is kept updated and protected because financial information deserves more care than an ordinary entertainment app.
My household verdict
After using Monarch as a household finance tool, I see its main strength in bringing separate financial threads into one conversation. Spending, net worth, investments, and goals make more sense together than they do in isolation. The app is particularly well suited to couples or families who want a regular review routine, need to coordinate shared expenses, and are willing to agree on account boundaries before building a common view.
I would recommend it to someone who feels that their money is scattered across too many places and wants more than a simple category list. I would also recommend setting it up slowly, keeping personal boundaries explicit, and checking important balances at the source before acting. Those habits prevent the dashboard from becoming either overwhelming or falsely reassuring.
I would not recommend it automatically to someone who needs strict privacy from other household members, wants a completely manual system, or will not make time to review and interpret the information. The app cannot create trust, settle disagreements, or decide which goals deserve priority. It can make those discussions more concrete, which is valuable, but the people using it still have to do the coordinating.
Overall, Monarch is a thoughtful choice for a shared financial routine when the household treats it as a planning companion rather than a surveillance screen. Its free installation lowers the barrier to trying the workflow, while the available in-app purchases mean I would evaluate the ongoing value before committing. For the right household, the clearest benefit is not simply knowing where the money went; it is making the next money decision together with fewer guesses.


